How to finance a tow truck: Apply with an equipment lender, get approved based on your credit, time in business, and the truck you’re buying, then make low monthly payments until it’s paid off. Beacon Funding has financed tow trucks since 1990, including new and used rollbacks, wreckers, and heavy-duty wreckers, even when you buy from a private seller.
Beacon Funding is a Northbrook, IL equipment finance company that provides tow truck financing to operators, from start-ups to established fleets. This guide answers the five questions to ask as you compare lenders.
In This Article…
- How Do I Finance a Tow Truck?
- Can I Finance a Used Tow Truck From a Private Seller?
- How Fast Can I Get Approved?
- Can a Start-up Get Tow Truck Financing?
- What Will My Monthly Payment Be?
- Ready to Finance Your New Tow Truck?
- Frequently Asked Questions
How Do I Finance a Tow Truck?
To finance a tow truck, choose the truck, apply with an equipment lender, get approved, and make low monthly payments until it’s paid off. Here is how that works with Beacon Funding:
- Pick your truck. Choose a new or used rollback, wrecker, or heavy-duty wrecker from a dealer or a private seller.
- Apply with a specialty equipment lender like Beacon Funding. We review your credit, time in business, and the truck itself.
- Speak to a financing expert. Within 24 – 48 hours, one of Beacon Funding’s expert financing consultants will contact you to discuss your financing options based on your goals.
- Get approved.
- Make low monthly payments until the truck is paid off.
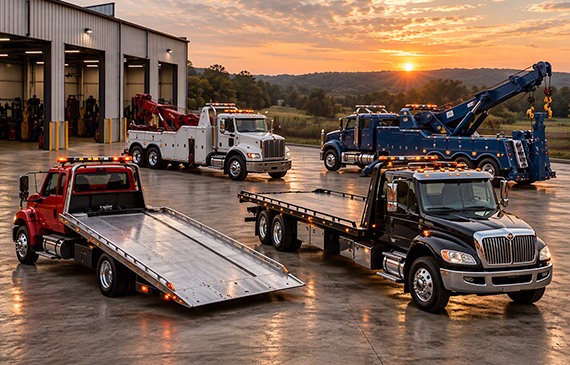
Step 1: Pick the right tow truck
Start with the work you expect to do, then match the truck to it. Price, condition (new or used), and upkeep determine how much you’ll finance and what your low monthly payment looks like.
|
Tow truck type
|
Common use
|
|
Rollback (flatbed)
|
Carries a vehicle on a flat bed. Suits disabled cars, dealer transport, and long-distance hauls.
|
|
Wheel-lift tow truck
|
Lifts a vehicle by its front or rear wheels for towing. Suits repossessions and tight streets or parking-lot jobs.
|
|
Wrecker
|
Uses a boom and winch to pull vehicles out of ditches and embankments. Suits accident recovery.
|
|
Heavy-duty wrecker
|
Tows and recovers semis, buses, and other large vehicles. Suits highway and heavy recovery work.
|
A tow truck loan or wrecker loan is equipment financing for the truck. You repay it in low monthly payments over an agreed term. Beacon Funding finances new and used rollbacks, wreckers, and heavy-duty wreckers.
Step 2: Apply for financing
Apply online with Beacon Funding and tell us about your business and the truck you want. Get pre-approved first to see your financing options before you commit to a truck.
START YOUR PRE-APPROVAL
Step 3: Speak to a financing expert
Within 24 – 48 hours, one of Beacon Funding’s financing consultants will contact you to discuss your financing options based on your goals.
Discussion points include:
- Down payment
- Low Monthly payment
- Term, which is how many months you pay
- What happens at term end
Step 4: Get approved and use your truck
Sign the agreement and finish the purchase. Then set up delivery, put your truck to work, and start generating revenue with it.
Why consider financing instead of paying upfront?
Financing can spread the purchase cost over time. That can help you:
- Keep cash available for payroll, fuel, insurance, and unexpected repairs.
- Add a truck sooner, so you can cover a wider area and take on more calls.
- Keep jobs moving when another truck is in the shop.
However, the payments still need to fit your cash flow, and financing costs can increase the total amount you pay
APPLY TO FINANCE A TOW TRUCK
Can I Finance a Used Tow Truck from a Private Seller?
Yes. Beacon Funding specializes in used tow truck financing, including trucks from private sellers.
Beacon Funding does not set strict age limits. It also will not structure terms that run past a truck’s financeable life, so the truck’s age and condition help set the term.
What should you check before financing a used tow truck?
- Mileage and overall condition
- Service history and maintenance records
- The hydraulic system, winch, boom, and flatbed, if the truck has them
- Likely repair costs. A cheap truck that keeps breaking down costs you work.
Before a private sale, ask Beacon Funding what papers it needs. These can include the seller's details, the truck's specs, and the agreed price. Have a qualified mechanic inspect the truck before you buy.
How Fast Can I Get Approved?
Beacon Funding makes most credit decisions within 24 hours, and its online application takes about 2 minutes. Approval timing depends on your application, the documents you provide, the lender’s review, and it is not guaranteed for every application. Final documentation and funding typically follow within a few business days once you select your equipment.
Preparing your information in advance can help keep the process moving.
Several factors may affect your application and the terms available.
- Credit history: Beacon Funding looks at personal credit and business credit if available, but does not require both. We also look at how you have handled loans, bills, and other equipment payments over time.
- Time in business: A longer history is business shows how your business handles good months and slow ones. Start-ups can still be approved.
- Cash flow: Recent bank statements (the last 3 months) show what comes in and goes out. They help show whether your business can comfortably support the payment.
- The truck: Its price, age, condition, and value all play a part, because the truck secures the deal.
- Industry experience: If you’ve been in towing for years, even working for someone else, that can count when you’re starting out on your own.
- Down payment: A larger down payment can help offset weaker areas in your application.
One weakness doesn’t mean denial. Strengths in one area can help balance out a weaker one, so it’s best to be upfront about anything in your history from the start.
Do I need a down payment?
Down payment depends on your business stage and credit. Established towing businesses typically put 0% to 10% of the equipment cost down, plus document fees, and well-qualified customers can often do sign-and-drive with just a document fee. Start-ups typically put down 20% to 25%, though some well-qualified start-ups may need less. Plan for upfront costs too, such as a security deposit, taxes, and inspection.
Before accepting an offer, confirm the required down payment, any fees, the monthly payment, and the total repayment obligation.
It is also important to keep enough cash available for regular business expenses after purchasing the truck. Spending all your available funds upfront can leave little room for repairs or other unexpected costs.
If you want to explore your potential options before choosing equipment, learn about pre-approval through Beacon Funding.
EXPLORE PRE-APPROVED OPTIONS
Can a Start-Up Get Tow Truck Financing?
Yes, subject to credit approval. Beacon Funding works with start-ups and established businesses, including towing businesses less than 12 months old. For start-ups, strong personal credit history is the biggest factor, alongside the down payment, industry expertise, and business plan. See Beacon Funding's start-up financing program.
How can a new towing business prepare?
- Plan the truck you want to buy.
- List the services you will offer and the area you will serve.
- Add up your running costs.
- Gather 3 months of business or personal bank statements, the truck's details and be ready to talk through your plans for the business.
- Consider a used truck if it can handle the work you expect.
What can a real tow truck deal look like?
Beacon Funding has financed a new medium-duty rollback priced at $270,881 for a towing business operating for less than 12 months. The Start-Up was able to finance the tow truck they needed using a 60-month Equipment Finance Agreement (EFA).
Another well-established towing business, needed new rollback priced at $123,000. Beacon Funding helped the business finance the rollback with $0 down and low monthly payments over a 72-month term. 100% financing helped the client conserve their cash while added the tow truck the needed sooner.
These examples illustrate the types of tow truck financing deals Beacon Funding has completed (they are not standard offers or guarantees of approval, pricing, or terms for another applicant).
The right financing structure depends on your business, the equipment, and the terms offered. If you’re interested in financing your next tow truck, contact Beacon Funding for a complimentary estimate.
EXPLORE START-UP FINANCING
Learn more about start-up equipment financing from Beacon Funding.
What Will My Monthly Payment Be?
Your payment depends on the truck's price, how much you finance, the term, and your down payment. No single payment fits every rollback, wheel-lift, or wrecker.
For payment ranges by truck class, see Beacon Funding's tow truck payment guide.
What affects your monthly payment?
- Truck price: A new heavy-duty wrecker costs much more than a smaller or used truck.
- Amount financed: A bigger down payment lowers the amount you finance but leaves you less cash.
- Term: A longer term can lower each payment but raises the total cost.
- Deal type: Financing structures have different payment schedules and end-of-term options. Check if you will own the truck at the end.
How can you estimate the payment?
Start by comparing the truck’s purchase price with your available funds and expected operating costs. Then use Beacon Funding’s equipment payment calculator to explore potential payment amounts.
An estimate is only a starting point. Your actual payment will depend on the terms available for your transaction.
Remember to budget for expenses beyond the financing payment, including:
- Insurance and licensing
- Fuel and routine maintenance
- Repairs and replacement parts
- Payroll and other business expenses
Consider how much revenue the truck needs to generate to cover these costs. Additional equipment may let you take on more work, but it does not guarantee more business or higher profits.
A financing agreement should suit the way your business operates, not just the price of the truck.
EXPLORE EQUIPMENT FINANCING OPTIONS
Ready to Finance Your Next Tow Truck?
Choosing the right truck is only part of the decision. You also need to understand the financing terms, upfront costs, and monthly payment before committing to a purchase.
GET STARTED FINANCING A TOW TRUCK
Beacon Funding provides equipment financing options for qualifying new and used tow trucks. Whether you are starting a towing business or expanding your fleet, exploring your options can help you make a more informed decision.
Frequently Asked Questions
1. What does Beacon Funding look at when approving tow truck financing?
Beacon Funding looks at your credit and pay history (strong credit preferred), time in business, cash flow (typically 3 months of bank statements), down payment, industry expertise and the truck you plan to purchase. Requirements and terms vary by application; learn more about how equipment financing works.
2. Can I finance a rollback or a wrecker?
Yes. Beacon Funding finances qualifying rollbacks, wheel-lift trucks, and wreckers, new or used, through its rollback and wrecker financing. The truck's age, condition, and price affect your terms.
3. Do I need a down payment to finance a tow truck?
Down payment depends on your business stage and credit. Established towing businesses typically put 0% to 10% down, and most start-ups should plan on 20% to 25% down plus upfront costs such as a security deposit, taxes and inspection. Explore potential options through Beacon Funding’s pre-approval program.
Financing is subject to credit approval. Terms, payment amounts, and eligibility vary by transaction, business, equipment, and other credit criteria.